Flood Insurance in Chicago: What Homeowners Should Know
Understanding flood risks, coverage, and questions to ask before the next storm
When rain becomes a home insurance concern
A stretch of heavy rain can change the feel of a neighborhood quickly. Water may collect along a street, run across a yard, or find its way into a basement. For homeowners, the damage can be stressful – and the insurance questions that follow are not always straightforward. Many people assume their homeowners policy covers any water damage, but the cause of the water is important. Flooding from rising or accumulating water is generally treated differently from a sudden plumbing leak. For people living in Chicago and the surrounding Chicagoland suburbs, understanding that difference before a storm can help avoid surprises later. This guide explains what flood insurance may cover, why a property’s risk is not always obvious, and what to review when considering protection. Actual coverage depends on the policy, its terms, limits, exclusions, and insurer.
Flood damage and homeowners insurance are not the same thing
A standard homeowners insurance policy may cover certain sudden and accidental water losses, such as damage caused by a burst pipe, depending on the policy and circumstances. Flooding, however, generally means water that comes from outside and affects normally dry land or property. Examples can include heavy rainfall that accumulates, overflowing waterways, or runoff entering a home.
The distinction can matter when a claim is reviewed. Water in a basement does not automatically mean the loss is covered – or excluded. The source, how it entered, and the policy wording all matter. Sewer or drain backup and sump-pump overflow may also be treated separately and could require optional coverage. Homeowners should read their policy and ask their insurance professional about unclear situations rather than assuming all water-related damage is handled the same way.
What can flood insurance help protect?
Flood insurance may provide coverage for a building, its contents, or both, depending on the policy selected. Building coverage may apply to parts of the structure and systems such as the foundation, electrical and plumbing systems, heating equipment, and built-in appliances. Contents coverage may help with eligible personal belongings, such as clothing, furniture, and certain electronics.
Building and contents protection can have separate limits, conditions, and deductibles. Some property or expenses may not be covered, and coverage for items stored in a basement or below ground may be restricted. It is worth asking how the policy treats finished basement areas, personal belongings, temporary living expenses, and cleanup costs. Do not assume every expense connected to a flood will be reimbursed.
Before choosing a policy, make a simple list of the parts of your home and belongings you would most want to protect. This can help you have a more useful conversation about limits and exclusions. Keep in mind that the list is a starting point; the policy documents determine what is actually covered.
Flood risk is not limited to waterfront homes
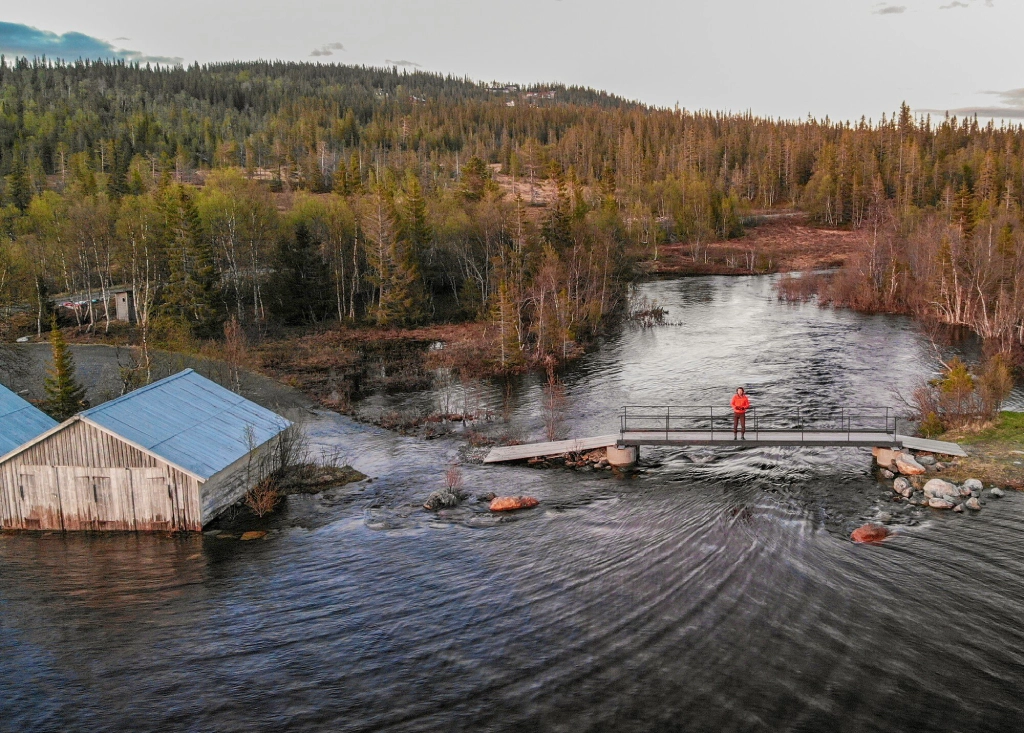
It is easy to associate flooding with a river or lake, but local flooding can happen in places that are not directly beside a body of water. Heavy rainfall, drainage capacity, grading around a home, and neighborhood conditions can all influence where water collects. A property’s flood-risk designation is useful information, but it is not a guarantee that flooding will or will not happen.
Homeowners can consider practical details about their own property: Does the home have a basement? Does water collect near the foundation after a storm? Have nearby streets or yards flooded in the past? Are gutters and downspouts directing water away from the home? These observations do not replace a formal risk assessment, but they can help identify questions to raise when reviewing insurance.
Even if a property has not experienced flooding before, conditions can change. New construction, changes in drainage, or an unusually intense storm may affect how water moves through an area. Thinking about risk ahead of time is generally easier than trying to understand coverage after damage has occurred.
What should you review before buying flood insurance?
Start by asking what the policy defines as a flood and what types of property are covered. Confirm whether the protection is for the building, contents, or both, and review the limits that apply to each. Ask about deductibles and whether separate deductibles apply to building and contents claims. A deductible is the amount you may need to pay toward a covered loss.
It is also important to ask about exclusions, restrictions, and waiting periods. Some policies do not take effect immediately, so the timing of a purchase can matter. If you own a condo, rent out a home, or use part of the property for a business, explain that situation when discussing coverage. The right policy structure may differ based on ownership and how the property is used.
Keep copies of policy documents and make an inventory of important belongings. Photos or videos of rooms and possessions, along with receipts for major purchases where available, can make it easier to document what you own. Store records somewhere they can still be accessed if your home is affected.
How flood insurance fits with your existing home coverage
Flood insurance is generally separate from a standard homeowners insurance policy. Reviewing both policies together can help you understand how they differ and whether there are gaps or overlapping terms to clarify. Ask your agent to explain which policy may respond to different kinds of water damage, including a plumbing leak, surface flooding, or a backup event. The answer depends on the wording of each policy, so it is better to ask before a loss than to rely on assumptions.
A regular review is especially useful after a major home improvement, a change in how the property is used, or a move. The amount of property you need to protect and the questions you should ask may change over time.
A few practical steps before the next heavy rain
Insurance is one part of preparing for severe weather. Homeowners can also check that gutters and downspouts are clear, keep important documents in a safe place, and avoid storing irreplaceable items directly on a basement floor. If water begins entering the home, prioritize safety and follow local emergency guidance. Do not enter standing water if electrical hazards may be present.
If flooding occurs, document damage when it is safe to do so, contact the insurer promptly, and follow its instructions. Keep records of communications, cleanup, and expenses. Avoid discarding damaged items before documenting them, unless immediate removal is necessary for safety or to prevent further damage.
Review your options with CG Insurance
Flood coverage is not automatically included in most standard homeowners policies, and the details can be difficult to sort through alone. If you are reviewing protection for a home in Chicago or the surrounding suburbs, contact CG Insurance to discuss questions and available options. A conversation can help you understand what to compare and what details to confirm for your property.